TL;DR

Get the latest gadgets delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
Amazon, Microsoft, Alphabet and Meta spent about $202 billion on property and equipment from July through September 2026, more than twice the year-earlier amount, according to figures compiled from company filings. The spending is being funded through a mix of operating cash, debt, leases, partnerships and equity; the scale and long terms of those commitments raise questions about who carries the risk if AI revenue grows more slowly.
Amazon, Microsoft, Alphabet and Meta spent about $202 billion on property and equipment from July through September 2026, more than twice their roughly $97 billion total a year earlier, according to a calculation based on their cash flow statements. As the companies expand data centers and buy servers and chips, recent disclosures show them drawing on borrowing, leases, partnerships and new shares alongside operating cash.
The spending figures are company-reported purchases of property and equipment, not a direct measure of AI spending alone. Amazon, which also builds warehouses, reported $77.3 billion for the quarter, up from $35.1 billion a year earlier. The company said the increase primarily reflected investments in artificial intelligence and maintained its expectation of about $220 billion in cash capital spending for 2026. Alphabet reported $51.4 billion, compared with $24 billion a year earlier, and kept its 2026 spending outlook at $195 billion to $205 billion.
Cash generation did not cover reported property and equipment purchases at three of the four companies in the quarter, according to the source’s comparison of filings. Amazon’s purchases exceeded operating cash flow by $34.9 billion, while Alphabet reported free cash flow of minus $9.1 billion and Meta minus $2.1 billion. Microsoft spent $39.4 billion and reported $58 billion in operating cash flow, leaving it positive on that comparison. These measures have different definitions: operating cash flow is not the same as free cash flow, and the comparison does not establish that every dollar of spending went to AI.
The financing disclosures span several instruments. Meta said it sold $25 billion of common stock and $12.5 billion of preferred shares during the week covered by the source. Microsoft issued $25 billion in bonds, including debt with a 40-year term. Amazon disclosed a loan facility of up to $80 billion secured by servers it plans to buy. Separately, the source’s tally of company filings puts future payments on leases that had not yet begun at about $1.02 trillion as of September 30. That figure is a calculation across four filings, not a company-reported combined total.
Capital • Compute • Commitment / Q3 2026
The Money Trail Behind AI Data Centers
Four technology giants sharply expanded property and equipment spending. The funding now spans cash, bonds, leases, partnerships and equity—raising a central question: who carries the risk if revenue grows more slowly than infrastructure?
Capital spending accelerated
Reported purchases cover property and equipment broadly, not AI alone. Amazon’s total also includes warehouses.
Amazon
$77.3B Q3 2026 • was $35.1BThe company said the increase primarily reflected AI investment. Its 2026 cash capital spending outlook remained about $220B.
Alphabet
$51.4B Q3 2026 • was $24BMaintained a 2026 spending range of $195B–$205B and signaled a significant increase in 2027.
Microsoft
$39.4B Q3 2026Reported $58B in operating cash flow, exceeding its reported property and equipment purchases.
Meta
Included In the $202B totalThe combined figure covers four companies. Meta’s quarter showed free cash flow of minus $2.1B.
Bars compare reported quarterly purchases for Amazon, Alphabet and Microsoft; Meta’s individual purchase amount was not provided in the source material. Cash flow and free cash flow use different definitions.
More than operating cash
Filings point to a wider funding toolkit as infrastructure plans grow in scale.
$225B raised
Amazon, Alphabet and Meta reported about $225B in long-term debt raised in the first nine months of 2026. Microsoft issued $25B in bonds in October, including debt with a 40-year term.
Up to $80B
Amazon disclosed a loan facility secured by servers it plans to buy, linking financing to equipment as well as to the company’s balance sheet.
$37.5B in shares
Meta said it sold $25B of common stock and $12.5B of preferred shares during the week covered by the source.
“A balanced mix of operating cash flow, investment-grade debt, strategic partnerships, and equity capital.”
Meta’s stated AI funding approach • October 26, 2026Follow the risk across time
Long commitments can outlast the equipment they support. The mismatch is a risk to watch, not proof that losses will occur.
Useful life vs. obligation
Who may be exposed?
Technology companies must cover financing, equipment replacement, leases and operating costs as services evolve.
Lenders and investors depend on companies and infrastructure projects generating enough returns to service debt and support equity value.
Partners, property owners and utilities may share exposure through project agreements, buildings and the capacity needed to supply reliable electricity.
Long power contracts can shape utility planning. The source does not quantify effects on consumer bills or identify specific contracts.
From funding source to financial exposure
Revenue against long-term obligations
The filings describe the commitments, but they do not settle whether future AI income will cover the full cost.
Questions for the next filings
How quickly is AI-related revenue growing, and how much supports equipment, debt service, leases and electricity?
How do capital spending forecasts change, and how are new projects financed across cash, debt, equity and partnerships?
Which participants ultimately bear costs if demand, technology or power requirements shift?
The article’s “bubble” framing is a question about exposure, not a finding that the market is in a bubble.
Figures are based on company disclosures and calculations described in the source material. The $1.02T future lease estimate combines four filings; it is not a company-reported total. Spending figures are not exact AI-only totals.
Who Carries the Data Center Bill
The financing mix matters because it determines who bears costs if new AI services earn less, or take longer to earn, than companies expect. Large technology firms can fund projects from profits and borrow against their balance sheets, but debt and lease payments persist over time. Investors who buy shares or bonds, lenders, partners and owners of data center properties may also be exposed to the outcome.
The source describes a mismatch in the useful lives and terms involved: servers are commonly written off over five to six years, while power contracts may run 15 to 20 years, data center leases up to 20 years and some bonds 40 years. These durations vary by agreement. If computing equipment needs replacement before long-term power or property obligations end, companies may face costs even as the technology changes. The source does not establish that such a mismatch will result in losses, but it identifies it as a key financial risk to watch.
Power costs extend the stakes beyond company balance sheets. Data centers need large, reliable electricity supplies, and long contracts can shape how operators and utilities plan capacity. The material does not quantify any resulting change in consumer bills or identify specific power contracts. For readers, the practical issue is whether investment produces enough revenue to cover financing and operating commitments without shifting unexpected costs to investors, lenders or electricity customers.
Products Worth Considering

Anker SOLIX C1000 Gen 2 Portable Power Station

Anker SOLIX S2000 Portable Power Station, 2,010Wh, 1,500W
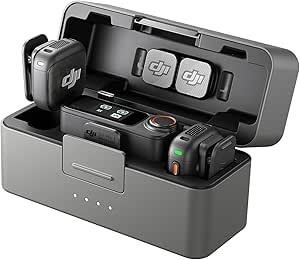
DJI Mic 3 Wireless Microphone System (2 Transmitters, 1 Receiver, Charging Case)
As an affiliate, we earn on qualifying purchases.
From Cash Funding to Mixed Finance
The source characterizes the earlier pattern as a decade in which large technology companies largely funded data center construction from operating profits. In 2026, spending accelerated enough that companies increasingly combined internal cash with external financing. The filings cited in the source show Amazon, Alphabet and Meta raising about $225 billion in long-term debt during the first nine months of the year; Microsoft’s $25 billion bond sale followed in October. The debt total is the source’s sum of reported cash flow statements.
Meta laid out its intended approach on October 26, saying it would fund AI investment through a “balanced mix of operating cash flow, investment-grade debt, strategic partnerships, and equity capital.” That statement is a company description of its financing plan, not evidence that each source will contribute a particular share. Amazon’s planned server-backed loan and the four companies’ unstarted lease commitments show how financing can also be tied to equipment or property rather than appearing solely as conventional borrowing.
The article also points to newer GPU cloud providers such as CoreWeave and to companies that own data center buildings as potential risk-bearing participants. It reports that CoreWeave senior notes carry interest rates of 8.5% to 9.75%. Those rates are specific to the cited notes and do not by themselves show the company’s overall borrowing cost or financial condition. The source’s broader question is how risk is distributed across the financing chain as AI infrastructure expands.
““Through a balanced mix of operating cash flow, investment-grade debt, strategic partnerships, and equity capital.””
— Meta, in a statement on October 26, 2026
Revenue Against Long-Term Obligations
The disclosures do not show how quickly AI-related revenue will grow or whether it will cover the cost of new equipment, debt service, leases and electricity. The reported capital spending totals cover property and equipment broadly, and Amazon’s includes warehouses; they cannot be treated as exact AI-only spending figures. The source also does not provide a comparable breakdown of the $1.02 trillion in future lease payments by company, project or payment year.
It is also unclear how much of the financing risk will stay with the technology companies and how much will be borne by lenders, investors, building owners, partners or utilities. The article’s “bubble” framing is a question about exposure, not a finding that the market is in a bubble. Future revenue, financing terms and power costs could change, and the cited commitments alone do not establish that any company will be unable to meet them.
Spending Plans and Financing Disclosures
Investors and customers can watch for the companies’ next quarterly filings and updates to their capital spending forecasts. Amazon’s stated plan is about $220 billion in cash capital spending for 2026. Alphabet kept its 2026 range at $195 billion to $205 billion and said it expects a significant increase in 2027. Those are company forecasts; actual spending may differ.
Future disclosures should clarify how much investment is funded by operating cash, borrowing, leases, partnerships and equity, as well as how data center expansion affects power contracts and operating costs. The material does not specify a single next milestone for the combined group. The key developing measure is whether AI-related revenue and cash generation rise alongside the infrastructure commitments.
Key Questions
How much did the four companies spend in the third quarter?
Amazon, Microsoft, Alphabet and Meta spent about $202 billion on property and equipment from July through September 2026, according to a sum of their cash flow statements cited in the source. The total is not limited to AI spending.
Why are the companies raising money if they are profitable?
The source says the companies are combining operating cash with debt, leases, partnerships and equity as infrastructure spending grows. Their profits do not mean that cash flow in a given period will cover every planned purchase and long-term commitment.
What does the $1.02 trillion lease figure represent?
It is the source’s combined calculation of future payments on leases, mostly for data centers, that had not started as of September 30, 2026. It is not a company-reported total, and the source does not give a full breakdown by company or payment year.
Does the spending prove there is an AI bubble?
No. The figures show rapid investment and multiple financing commitments, but they do not establish that the market is in a bubble. A central open question is whether future AI revenue will cover the costs and who would bear losses if it does not.
Source: Thorsten Meyer AI